1
Currency markets can appear oddly quiet in turbulent times.
2
This stability hides the fact that currencies can be pulled in opposite directions.
3
Some investors are looking to currency markets not just for potential protection, but as a distinct source of returns that may behave differently from shares and bonds.
Currency markets are often described as the purest expression of the global economy. Every day, they absorb views on growth, inflation, interest rates, politics and risk appetite, all in real time.
That is what makes their recent behaviour so striking. At a moment when investors have had plenty to worry about, from geopolitical tension to shifting central-bank policy, many major currencies have remained surprisingly subdued. Exchange rates have moved, but not with the force many would expect.
At first glance, that may seem reassuring. In reality, unusual calm in foreign exchange can be just as revealing as dramatic swings. Sometimes it suggests that powerful forces are cancelling each other out.
Today’s calm in currency markets may not last.
Sometimes exchange rates are shaped by several competing influences at once, and those forces do not always point in the same direction.
A currency may be supported by higher interest rates, for example, even if investors are uneasy about that country’s politics or public finances. Another may weaken because growth is slowing, but stay more stable than expected because similar problems exist elsewhere.
That helps explain one of the biggest recent anomalies in foreign exchange: the recent low level of volatility in developed-market currencies.
That is surprising because the backdrop has hardly been quiet. Energy prices have risen, the Middle East has been unstable, and concerns about debt and fiscal policy have grown in several economies. Normally, that mix would be expected to trigger sharper currency adjustments.
Why currencies do not always react as expected
The US dollar sits at the centre of this puzzle.
On one side, it faces clear headwinds. Concerns about America’s fiscal position and wider policy uncertainty might be expected to weaken confidence. On the other side, US interest rates remain relatively high, which makes dollar assets more appealing to investors seeking income.
In effect, the dollar is being tugged in opposite directions. Investors may worry about the longer-term picture, but they are still being paid relatively well to hold it. Those conflicting signals have helped leave the dollar without a decisive trend. And because the dollar is involved in so many global trades, that indecision tends to dampen movement elsewhere too.
More broadly, the world economy has also been more resilient than many expected. When growth holds up and data remains fairly stable, investors have less reason to make large, sudden changes to their currency positions. That can keep exchange rates trapped in narrow ranges, even when the headlines suggest they should be moving more.
The strange case of the steady dollar
Unusual calm in foreign exchange can be just as revealing as dramatic swings.
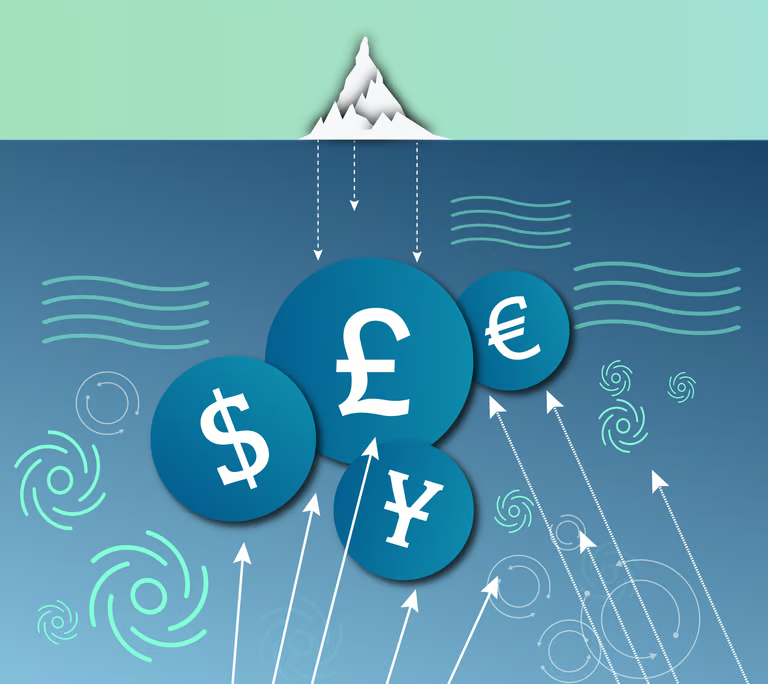
Quiet currency markets are not always efficient ones. In fact, periods of calm can allow mispricings and anomalies to build up. That is because currencies reflect not just economic fundamentals, but also investor behaviour – positions can become crowded and assumptions can harden. Some currencies can look too cheap or too expensive compared with long-run patterns, interest-rate differences or changing growth prospects.
An investor does not need a crisis to find opportunity. Sometimes the opening comes from recognising that two currencies are not behaving in line with the underlying forces that usually drive them.
For example, a currency offering a higher interest rate may attract buyers for a long time, even if the economic case for that strength starts to weaken. Another may stay under pressure because sentiment is poor, even after the fundamentals begin to improve. These disconnects can create openings for investors.
Calm markets can still contain opportunity
Traditionally, many investors treated currencies as a background issue, something to hedge or manage rather than a return source in its own right.
That is changing. In our conversations with clients, it’s clear that some are now looking at currency alpha as a way to diversify portfolios, especially after periods when equities and bonds have fallen together. The appeal is straightforward: if currency returns are driven by different factors, they may offer a source of performance that does not simply mirror the direction of stock or bond markets.
In practice, investors tend to look for returns from a mix of signals rather than one single big call. Some focus on carry, which means earning the difference between interest rates in different countries. Others look at momentum, or the tendency for trends to persist for a time. Some watch valuation, asking whether a currency looks cheap or expensive against its longer-term norms. There are also more qualitative judgments around macroeconomics, policy credibility and how markets may react if a widely held view starts to unwind.
None of this is easy. Currency investing can be fast-moving and unforgiving. But for investors seeking broader diversification, it can be a useful part of the toolkit.
How investors try to generate returns from currencies
Quiet currency markets are not always efficient ones. In fact, periods of calm can allow mispricings and anomalies to build up.
Today’s calm in currency markets may not last. If global growth slows, if interest-rate expectations shift or if geopolitical risks ease or worsen, exchange rates could move much more sharply.
So, it’s important to remember that this quiet period is not just a lull. It is a reminder that currency markets often tell a more complicated story than the headlines suggest.
For investors, that complexity can be a challenge. But it can also be an opportunity, especially when currencies are being pulled in different directions and markets appear calmer than the world around them.
Currency calm should not be mistaken for simplicity
Francesca Fornasari is Head of Currency at Insight Investment. She is responsible for overseeing Insight’s team of currency investment professionals, who manage currency solutions ranging from foreign exchange hedging to currency alpha.